Back
Automatically translated version. May contain inaccuracies compared to the original.
📱 The court canceled 10,9 million UAH in fines: the State Tax Service tried to “attribute” proceeds from selling Apple equipment to the income of a sole proprietor
This was reported by the Telegram channel "Sudom po skhemakh" with reference to Case No. 320/6861/26.
🛍 Essence of the conflict and the State Tax Service’s claims
The Kyiv tax authority audited the activities of sole proprietor Yakubenko Vitalii Oleksandrovych, who was engaged in retail trade of electronics and high-value Apple equipment.
Based on the audit, the State Tax Service issued a series of tax notices and decisions totaling more than 10,9 million UAH. The bulk of that amount was a penalty under the Law on Cash Registers — 10,2 million UAH for alleged sales of unrecorded goods, as well as assessments of the single tax together with penalties totaling more than 645 thousand UAH.
The tax inspectors’ scheme was that during the audit they simply “did not notice” the consignment nature of the trade and included the entire volume of proceeds (over 9 million UAH) from the sale of equipment in the entrepreneur’s personal income. This allowed the State Tax Service to claim that the sole proprietor allegedly exceeded the annual income limit for the 3-th group of the simplified tax system and was obliged to switch to the general system.
📄 The entrepreneur’s position
The plaintiff proved in court that the sale of electronics was carried out under consignment agreements, under which his net income is only a 1% commission fee, not the full value of the sold gadgets.
The sole proprietor provided a complete set of primary documents — contracts, acceptance-transfer acts for inventory, the commission agent’s reports, and bank statements — which confirmed that the entrepreneur’s actual income did not exceed the permitted limit.
⚖️ What the court decided
The Kyiv District Administrative Court (Judge Marych Ye.V.) found the tax authorities’ actions unlawful and drew attention to the following key points:
• Commission agent’s income: According to paragraph 292.4 of Article 292 of the Tax Code of Ukraine, when services are provided under consignment agreements the income of a single tax payer is exclusively the amount of the received commission fee, not the entire proceeds from the sale of the goods.
• Documentary evidence: All primary documents were submitted in full. The State Tax Service’s claims about the absence of waybills (TTN) were rejected by the court because the goods were transported in the entrepreneur’s own car (Ford Focus), which was confirmed by the relevant orders.
• Personal responsibility: The court emphasized that potential violations by counterparties cannot be the basis for accusing the commission agent of fictitious transactions (Art. 61 of the Constitution of Ukraine).
❌ Summary
All tax decisions regarding the additional assessment of the single tax and the application of penalties totaling 10,9 million UAH were recognized as unlawful and canceled by the court decision dated 09 September 2026.
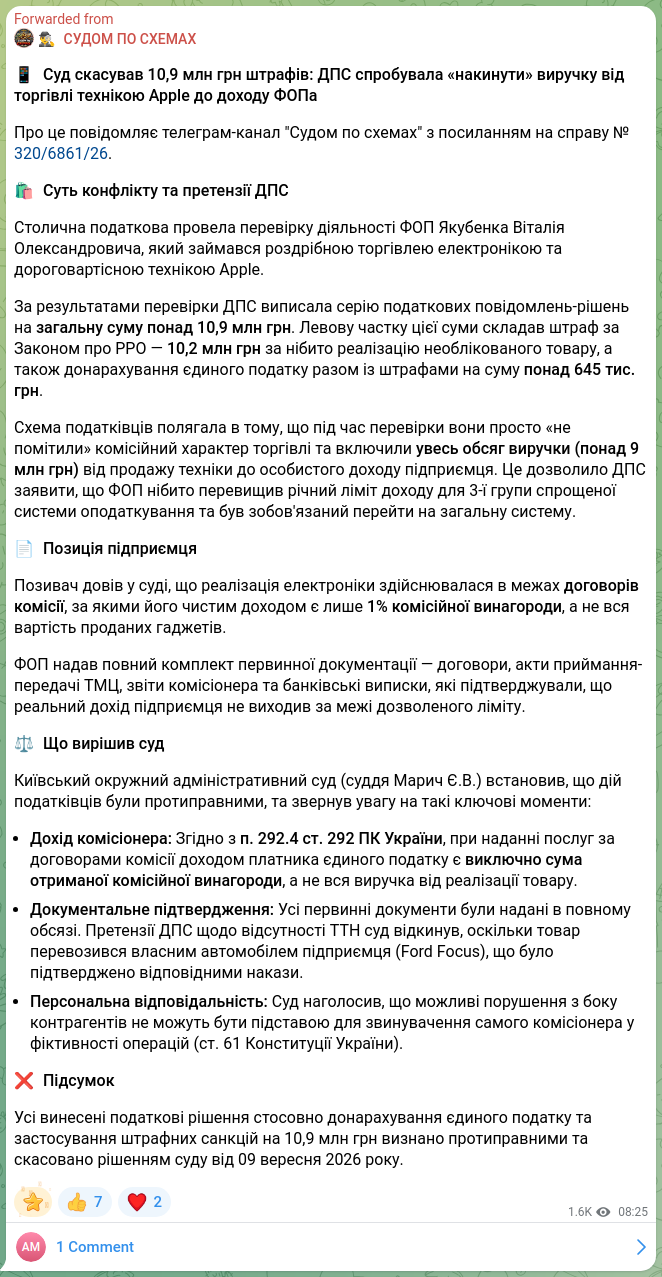


 Telegram publication